Trade Lifecycle for Quants: From Booking to PnL, Risk, XVA & Model Validation
₹799
Use coupon code TRADECYCLE10 at checkout for 10% off.
About this resource
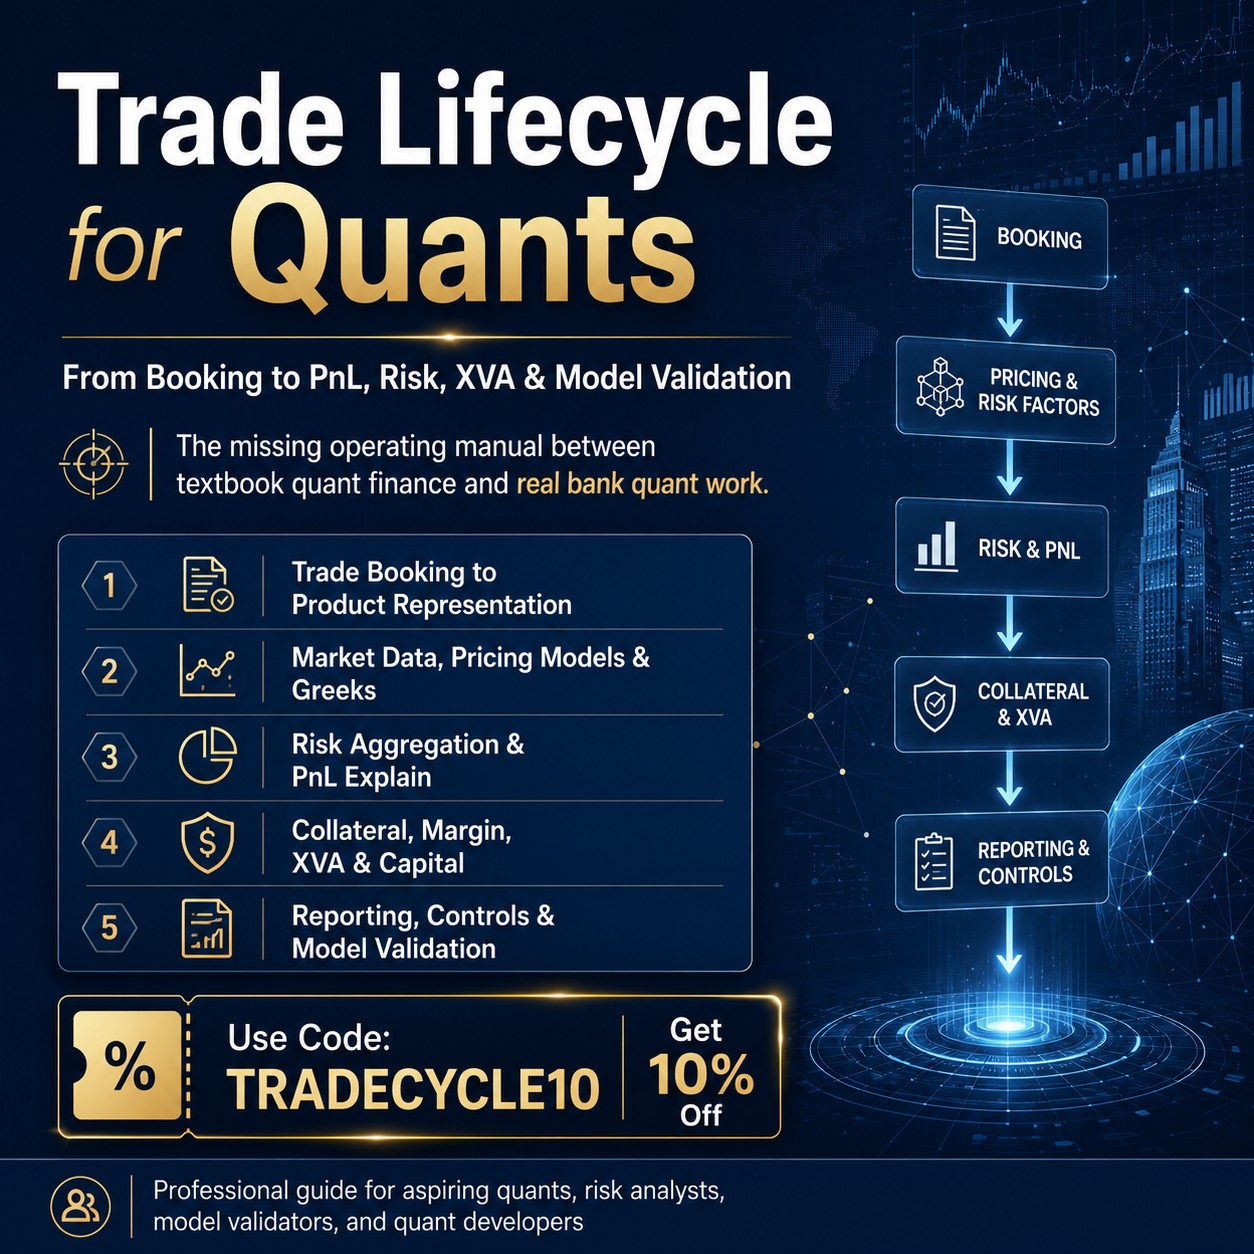
Trade Lifecycle for Quants: From Booking to PnL, Risk, XVA & Model Validation The missing operating manual between textbook quant finance and real bank quant work. Most aspiring quants learn pricing formulas, stochastic calculus, Greeks, and models in isolation.
But real banking work is much bigger than that. A trade does not stop at pricing. It moves through booking, product representation, market data, valuation, Greeks, risk aggregation, PnL explain, limits, collateral, XVA, capital, reporting, and model validation.
Trade Lifecycle for Quants is a professional, practitioner-style guide created for aspiring quants, risk analysts, model validation candidates, quant developers, and finance students who want to understand how real banking architecture works beyond textbook formulas.
Use coupon code TRADECYCLE10 to get 10% off. What This Guide Covers This guide explains the complete life of a trade inside a bank: Trade Booking → Product Representation → Market Data → Pricing Model → Greeks → Risk Aggregation → PnL Explain → Limits → Collateral & Margin → XVA → Capital → Reporting → Model Validation Instead of studying pricing models in isolation, you will learn how models, trades, market data, risk, PnL, XVA, controls, and validation are connected inside a real financial institution.
What You Will Learn How trades are booked and what fields really matter How vanilla, exotic, structured, linear, and non-linear products are represented How market data such as curves, surfaces, fixings, calendars, and spreads feed pricing systems How pricing models are selected, implemented, challenged, and monitored How Greeks and sensitivities flow into risk systems How risk is aggregated across trade, portfolio, desk, counterparty, and entity levels How PnL explain works through clean PnL, dirty PnL, explained PnL, unexplained PnL, and residuals How limits, stress testing, VaR, and exposure metrics connect to trade-level economics How collateral, margin, netting, and CSA terms affect valuation and risk How XVA connects counterparty credit risk, funding, collateral, funding cost, and capital How model validation reviews pricing models, assumptions, limitations, monitoring, and remediation How to explain trade lifecycle concepts in interviews using a professional banking lens What Makes This Resource Different This is not another formula-only quant finance note.
It is designed to teach the operating system of real quant work. Inside, you will find: Practitioner insights Short tricks Mnemonics Interview flags Mini case studies Failure-mode diagnostics Control checklists Evidence-log templates Desk-style explanations Model validation perspectives Professional interview answers The goal is simple: To help you understand what actually happens after a trade is booked — from pricing and Greeks to PnL, risk reporting, XVA, capital, and model validation.
What you get
- Instant digital delivery by email after purchase
- Written by a practising quantitative risk modeller
- Desk-focused material, not textbook theory
Delivery & refunds
Access is delivered by email immediately after payment. See our terms and privacy policy.
Frequently asked questions
How is Trade Lifecycle for Quants: From Booking to PnL, Risk, XVA & Model Validation delivered?
Access is delivered digitally by email after payment is verified. Keep the purchase email so you can find the delivery link later.
Who is Trade Lifecycle for Quants: From Booking to PnL, Risk, XVA & Model Validation designed for?
It is designed for quantitative-finance candidates and practitioners who want desk-focused explanations, practical diagnostics and interview-ready reasoning.
Where can I review the price and purchase details?
Use the product details link on this page to review the current price, any available offer and the secure checkout information before buying.
Related resources
- Fast Greeks & Initial Margin for Quants — AAD, SIMM & MVA Production Lab
- Market Microstructure & Market Making for Quants: 100-Page Playbook + Python Lab
- The Vol Surface Construction Playbook — SVI, SSVI, Static Arbitrage & Dupire Local Volatility
- Quant Researcher Interview Playbook: Time Series, Signals & Statistical Research
- 50 FX Derivatives Problems for Quant Interviews
Get Trade Lifecycle for Quants: From Booking to PnL, Risk, XVA & Model Validation